



The 5 Advantages of CRM in the Banking Sector

KEY TAKEAWAYS:
- A banking CRM organizes customer relationships, conversations, and follow-up work; it is not automatically the bank’s transaction ledger or loan decision system.
- Its practical advantages include more consistent service, clearer case ownership, less repetitive work, and better-targeted outreach when data and permissions are fit for purpose.
- Connect only approved data, define access by role, and keep consequential financial decisions in their authorized systems with human review where required.
- Test value in one workflow first. Compare pilot results with a baseline and track service quality, adoption, data quality, and customer-contact guardrails. For related controls, see this guide to fintech cybersecurity.
The advantages of CRM in the banking sector come from making customer conversations and service work easier to coordinate. A CRM can help authorized employees see relevant relationship history, route requests to an owner, complete follow-ups, and tailor outreach to a customer’s needs. The value depends on accurate integrations, clear data-access rules, usable workflows, and staff adoption. A CRM should support those tasks, not be treated as the source of truth for balances or a substitute for approved lending decisions.
For a bank deciding whether to buy or expand a CRM, the useful question is not whether the platform promises a “360-degree view.” It is whether a specific team can resolve a real customer problem more reliably without copying unnecessary data or creating extra work. The five advantages below explain what a CRM can improve, where its limits sit, and how to test whether it fits.
What Is CRM In Banking?
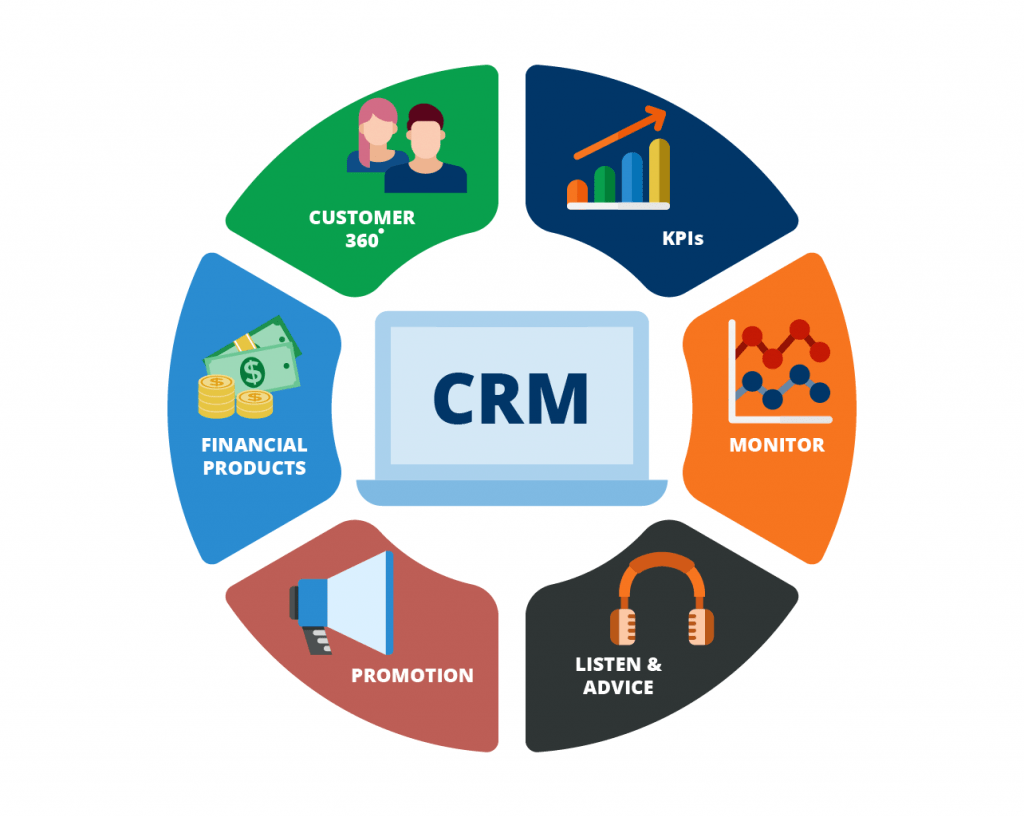
Banking CRM is software and a set of working practices for organizing customer profiles, interactions, requests, and follow-up across teams. It helps relationship managers and service employees understand the context of a conversation and coordinate the next action. Depending on the bank’s design, CRM data may come from branch, contact-center, web, or mobile channels.
A CRM is not automatically the authoritative record for deposits, payments, balances, identity checks, or loan underwriting. Those records and decisions belong in the systems the bank has designated for them. A CRM may display limited information or start a workflow through an approved integration, but the bank must define which system owns each field, how fresh the information is, and who can see or change it. For example, Salesforce describes its Financial Services Cloud as connecting data from core banking and other platforms; that is a vendor’s product description, not proof that every CRM integration is safe or suitable for every bank.
This distinction matters because a unified customer view should mean useful context for an authorized task, not unrestricted access to every account or transaction. Banks should map each proposed CRM use to a named workflow, permitted data, accountable owner, and correction path before rollout.
5 Advantages Of CRM In The Banking Sector
A banking CRM creates value when it improves a defined customer or employee workflow. The five advantages below are related but distinct: a better relationship view supports service, routing supports speed, automation reduces repeated steps, and governed data can make outreach more relevant. None guarantees higher retention or revenue on its own.
1. Build A More Useful Customer Relationship View
A CRM can help an authorized employee find the context needed for the current interaction without searching separate inboxes or spreadsheets. Depending on the integration and permissions, a profile might show contact preferences, open service cases, prior conversations, or the status of a referral. The goal is not to duplicate every customer record. It is to surface a small, accurate set of information that helps the employee answer the request or hand it to the right team.
That view is only as useful as its data quality. A stale phone number, duplicate customer profile, or unassigned service case can lead to a poor experience even when the CRM looks comprehensive. Banks should identify a data owner for important fields, display source and last-updated details where needed, and give employees a clear way to report a mismatch. Customer context should also be limited by role and purpose rather than exposed to every user by default.
2. Support More Consistent Service And Retention
A CRM can make service more consistent by recording who owns a request, what the customer has already been told, and when the next follow-up is due. If a customer contacts the bank again, an authorized employee can continue from the open case instead of asking the customer to repeat the full history. This is especially useful when work moves between a contact center, branch, and relationship team.
Better follow-up may help a bank address unresolved friction before it damages a relationship, but software cannot guarantee loyalty. The bank still needs a clear escalation path, realistic service commitments, and staff empowered to resolve the underlying issue. Track whether requests are resolved and customers receive promised updates; do not interpret a logged interaction or campaign response as proof of long-term retention.
3. Coordinate Inquiries And Service Work Faster
CRM routing can reduce avoidable handoffs when a request arrives through a branch, website, mobile app, or contact center. Consider a customer who asks about a mortgage through the mobile app. The CRM can create a case, route it to the correct team, and make the permitted conversation history available to the assigned adviser. A safe workflow could look like this:
- Capture the request: Record the customer’s question, channel, preferred contact method, and any consent or communication preference relevant to follow-up.
- Assign an owner: Route the case using the bank’s approved queue or assignment rules, and set a response target defined by the service team.
- Check the right system: The adviser confirms identity and checks eligibility, rates, and application requirements only in the bank-approved systems for those tasks.
- Record the next step: The CRM logs the contact, owner, and promised follow-up so another authorized employee can see the case status.
- Close or escalate: The team confirms that the question was answered or sends the case to a specialist. The CRM tracks the service handoff; it does not calculate an underwriting score or approve a loan.
This workflow can make ownership and response delays visible. It does not make the mortgage decision itself faster unless the separate application, verification, and underwriting processes also improve. A bank should measure the CRM’s contribution at the enquiry and service stages, not attribute a final approval or funding outcome to case routing alone.
4. Reduce Repetitive Staff Work
Reminders, case queues, reusable templates, and status updates can reduce manual searching and repeated data entry. A service employee might see which cases are waiting, which need a customer response, and which have reached an escalation point. A relationship manager may also use a meeting checklist to prepare, as long as the underlying information is current and the employee can verify it.
Automation should remove avoidable steps, not hide decisions or create workarounds. If staff must update the same field in the CRM and another system, or dismiss irrelevant reminders, the workflow may lower adoption rather than improve productivity. Involve frontline employees in process mapping, train them on exceptions as well as the standard path, and compare task time and rework before and after the pilot. Keep a human owner for sensitive communications and decisions.
5. Make Outreach More Relevant And Measurable
A CRM can help marketing and relationship teams organize audiences and follow-up based on information the bank is permitted to use. For example, a team could track whether customers who requested information about a service received a timely response, or compare the response to a clearly defined campaign. The workflow should respect contact preferences and any applicable consent and suppression rules.
Segmentation is not a license to infer sensitive traits, send unwanted offers, or treat a model’s recommendation as a customer’s need. Review audience definitions, data sources, message frequency, and opt-out handling before a campaign. Measure delivery, response, complaints, and conversion to a next step such as an application; keep campaign attribution separate from credit approval or other decisions made by authorized systems.
Integration And Data Controls Banks Should Set
CRM integrations can reduce repeated work, but a bank should decide what crosses each system boundary before connecting data. Start with the task: does a service employee need a status, a verified contact detail, or a link to an authoritative record? Exposing an entire transaction history when a case status would suffice increases complexity and may create unnecessary data risk.
For every field or event sent to a CRM, document its source, owner, permitted purpose, refresh timing, user roles, retention rule, and correction path. Design for failed or delayed integrations too. If the CRM cannot confirm that information is current, it should show an appropriate status or direct the employee to the authoritative system rather than present stale data as fact.
- Access: Apply role- and task-based permissions, review them when employees change roles, and restrict sensitive fields to users who need them.
- Data movement: Prefer the minimum fields needed for the workflow; define how APIs authenticate, log access, handle errors, and prevent duplicate or conflicting updates.
- Customer contact: Carry communication preferences and applicable consent or suppression signals into the workflow, and make the responsible owner clear.
- Governance: Assign owners for data quality, access reviews, integration changes, incident escalation, and employee training. Confirm legal and regulatory requirements with the bank’s own compliance team for its jurisdictions.
CRM is one part of a broader financial technology environment, not a replacement for security and compliance controls. A bank planning related integrations can also review this overview of RegTech software and compliance workflows. The exact control design should follow the bank’s risk assessment and local requirements; a software feature alone does not establish compliance.
How To Pilot And Measure A Banking CRM
A CRM pilot should test one bounded workflow, such as routing mortgage enquiries or tracking a specific service request, before expanding to more teams. Choose a baseline period and a comparable channel or team where practical. Agree in advance on the pilot window, primary outcome, guardrails, data definitions, and the thresholds that would lead the bank to continue, adjust, or stop. Those thresholds depend on the bank’s starting point; there is no universal CRM benchmark.
| Measure | Suggested Owner | How To Define It | Guardrail Or Interpretation |
|---|---|---|---|
| Time to first response | Service lead | Elapsed time from a valid enquiry arriving to the first substantive response; report median and an agreed upper percentile. | Separate channels and business hours; faster replies do not count as success if resolution or customer experience worsens. |
| Follow-up completion | Team or branch manager | Share of due follow-ups completed by the agreed date, using a consistent definition of “due” and “completed.” | Audit a sample for accurate logging; do not reward closing cases without resolving the request. |
| Qualified enquiry to application | Product or sales lead | Share of eligible enquiries that proceed to an application within the defined observation window. | This is a progression measure, not a loan-approval rate or a signal that CRM should determine eligibility. |
| Active use and workflow adoption | CRM product owner | Share of in-scope employees completing the required workflow in CRM, alongside task-time or duplicate-entry feedback. | Do not use logins alone as adoption; check whether the system adds work or drives shadow spreadsheets. |
| Data quality and contact guardrails | Data steward and compliance owner | Track required-field completeness, duplicate or stale records, access exceptions, and contact-preference handling. | Set acceptable limits before launch and pause or remediate if a serious access, data, or unwanted-contact issue occurs. |
Record the baseline and pilot results using the same definitions, channels, staffing assumptions, and time windows. Note material changes such as a policy update, seasonal demand, or staffing shift that could affect the comparison. The pilot report should show observed results separately from proposed targets, explain missing data, and include employee and customer feedback where available. If the workflow improves speed but increases rework or complaints, adjust the routing, training, or integration before scaling.
Further reading:
- How To Create A Financial App: Steps, Features, And Costs
- FinTech Ecosystems: A Detailed Guide to Transform Finance
How To Choose A CRM Approach
Choose a packaged, configurable, or custom CRM by comparing the fit to the bank’s documented workflow and operating constraints, not by assuming one option is inherently safer or more compatible. Ask each vendor to demonstrate the same realistic scenario, including integration failure, permission boundaries, audit history, mobile use if required, and handoff to the system of record.
- Packaged CRM: Consider it when standard capabilities meet the workflow and the vendor can support the bank’s integration, access, hosting, support, and data requirements.
- Configured CRM: Consider it when the platform fits but needs controlled changes to fields, roles, queues, forms, or reports. Keep configuration documented and test it after upgrades.
- Custom development: Consider it only when a material, documented gap cannot be addressed through configuration or an existing product. Include integration maintenance, security testing, operational support, staff training, and total lifecycle cost in the decision.
Before signing, ask for a clear data-flow diagram, responsibility matrix, implementation plan, test evidence, incident and support process, exit or data-export terms, and references for comparable work. Compare total cost over the expected operating period, not only the initial license or build quote. A partner’s general software-development capability is not proof of a banking CRM track record, so request evidence that matches the scope you need. If a verified gap does justify custom work, review the provider’s software development services alongside other candidates using the same evidence and controls.
FAQs About CRM In Banking
These answers clarify three decisions that often arise after a bank defines its CRM workflow: which system owns the record, how customer information may be used, and what evidence to collect before expanding a pilot.
Does A Banking CRM Replace Core Banking Software?
No. A CRM manages relationship context and customer-facing workflows. The bank’s designated core and other authoritative systems remain responsible for records such as balances and transactions; integrations should expose only the information needed for an approved task.
Can A CRM Use Transaction Data To Recommend A Product?
It may support an approved workflow that uses selected data, but the bank must decide whether that data may be used for the purpose, who can access it, and how recommendations are reviewed. A CRM suggestion should not be treated as a credit decision, and customer preferences and applicable consent rules still matter.
How Can A Bank Measure CRM Value Before A Full Rollout?
Pilot one workflow with a documented baseline, named owner, defined observation window, and pre-agreed continue/change/stop criteria. Track an outcome such as response time or completed follow-ups together with guardrails for data quality, access, customer contact, rework, and employee adoption. Report the results as observations from that pilot, not as a universal return estimate.
A Practical Decision Rule For Banks
A CRM is worth testing when a bank can name a customer-facing workflow that currently loses context, delays ownership, or makes follow-up hard to verify. Define the permitted data and the system of record first, then pilot the smallest change that can address the problem. Expand only if the measured service or workflow outcome improves without breaching the bank’s agreed quality, access, customer-contact, and operating guardrails.
The practical advantage of CRM in banking is better-coordinated relationship work, not a promise of automatic loyalty, revenue, compliance, or loan approvals. A clear workflow, accountable owners, and evidence from a controlled pilot give decision-makers a stronger basis for choosing a platform or deciding not to proceed.
Also published on

Share post on




Related Articles


The 5 Advantages of CRM in the Banking Sector
The 5 Advantages of CRM in the Banking Sector Published October 19, 2026
What Are Enterprise Applications? How They Support Business Operations
What Are Enterprise Applications? How They Support Business Operations Published September 21, 2026
10 Best CRM Software Options For Small Businesses In 2026
10 Best CRM Software Options For Small Businesses In 2026 Published September 18, 2026